Quick answer
Term life insurance pays a death benefit when the insured person dies while coverage is in force during a stated period. It usually begins with a lower premium than permanent coverage and has no cash value. Match the term to the financial need, then inspect renewal premiums, the conversion deadline and what happens when the initial term ends.
The first premium is easy to compare. The harder question is whether the coverage and the need end at the same time.
How does term life insurance work in Canada?
You apply for a death benefit and an initial coverage period. If the insured person dies while the policy is in force and the claim meets the contract, the named beneficiary receives the benefit. If the insured person survives the term, the policy may expire, renew or be converted according to its wording.
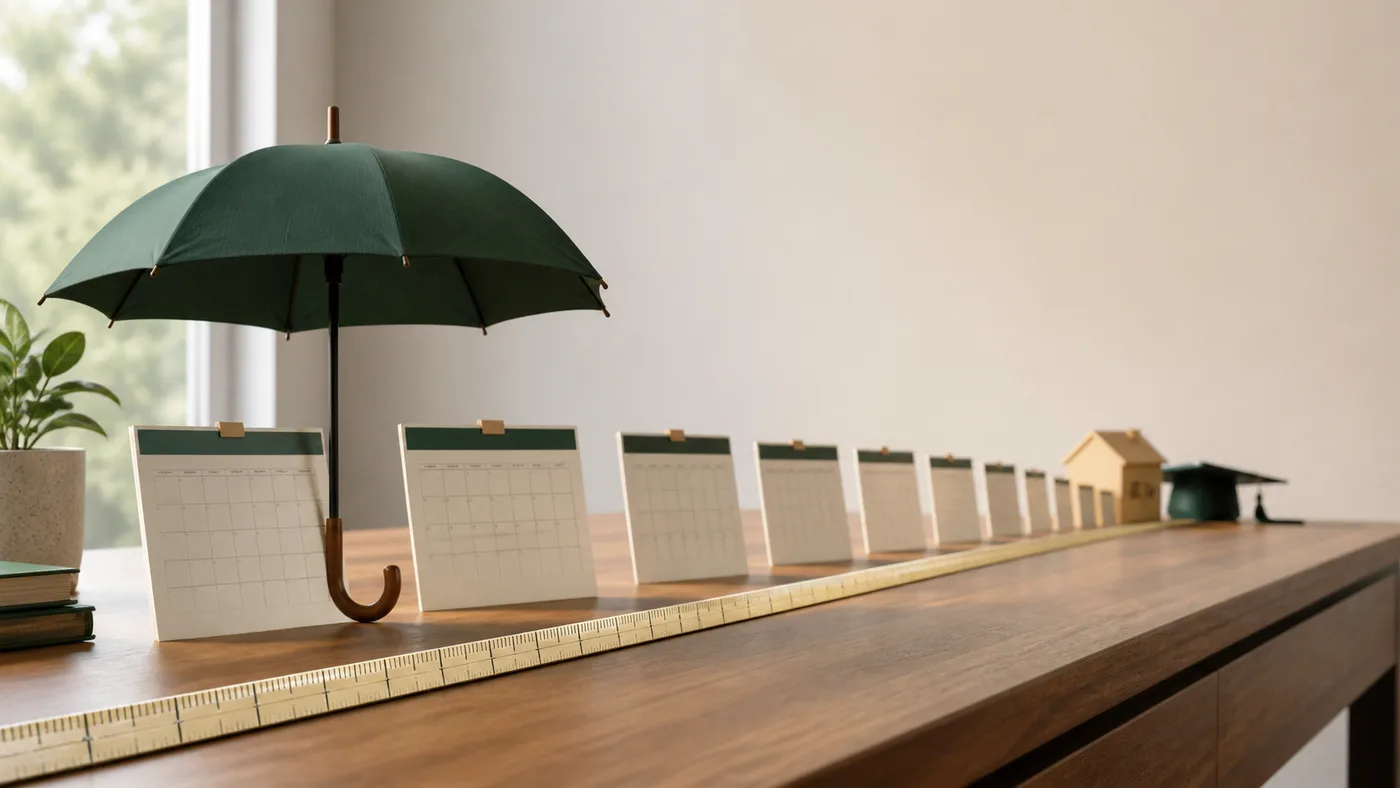
Put the need and contract on one timeline
What is the difference between expiry, renewal and conversion?
Expiry ends coverage, renewal continues eligible term coverage, and conversion changes eligible coverage to a permanent policy. They are different outcomes, with different deadlines and costs.
Three outcomes to check before the term ends
| Outcome | What changes? | When does it matter? |
|---|---|---|
| Expiry | Coverage ends if it is not continued under the contract. | Check whether the original need has ended or a coverage gap would remain. |
| Renewal | Eligible term coverage continues for another period; the policy's renewal premium applies. | A temporary need continues. Check renewal cost and the final renewal age. |
| Conversion | Eligible term coverage changes to an available permanent policy under its conversion option. | A need may last for life. Check the conversion deadline, eligible amount and new premium. |
What happens when term insurance renews?
A renewable contract may continue without a new health application, subject to its limits, but the premium normally follows the renewal schedule in the policy. That schedule can rise sharply because the insured person is older and the insurer is continuing coverage under the renewal provision. Read every future renewal amount available today.
What is a term insurance conversion option?
A conversion option may allow the owner to exchange eligible term coverage for an eligible permanent policy without new medical evidence before a deadline. Conversion is not the same as renewal. It changes the policy type, premium and available products. The contract specifies the deadline, maximum amount and choices available.
The Autorité des marchés financiers life and health insurance guide distinguishes renewable term coverage from conversion to permanent coverage. Its general comparison is a starting point; your policy determines the options and premiums available.
How do you choose the length of a term?
List each temporary obligation and its expected end date: income replacement, debt, education support, business debt or another dependency. The longest important obligation creates a starting point. Then compare affordability, the risk of renewing while health has changed and whether a ladder of different terms adds useful precision or unnecessary complexity.
How much term coverage is enough?
Estimate the cash needed after death: income replacement, debt, care, education, final expenses and business commitments. Subtract liquid assets and coverage that would actually remain available. Avoid using one income multiple without checking what it is meant to fund. The amount and the duration are separate calculations.
Use the life insurance needs calculator to organize the amount estimate, then compare each obligation’s end date with the policy timeline above. The estimate is a planning aid, not a quote or an underwriting decision.
Do you get money back when term insurance ends?
Standard term insurance generally has no cash value, so surviving the term does not normally produce a payment. Some contracts add separate return features, which change cost and wording. Read the exact policy rather than assuming the feature from the product name.
Does conversion mean the premium stays the same?
No. Conversion may remove the need for new medical evidence within the contract rules, but the new permanent policy has its own premium based on the conversion terms and age. Ask which products are eligible and request the resulting premium before the deadline.
Sources and review notes
The expiry, renewal and conversion comparison was checked September 9, 2026 against the federal life insurance guide and the life and health insurance guide (2012, with a 2019 addendum). These explain general mechanics; current policy wording controls eligibility, deadlines and premiums.